Most people think a personal injury case has to go to court to be worth anything. It doesn’t. Sometimes the evidence is strong enough that the case resolves before a lawsuit is even filed.
Here’s how I recovered full insurance policy limits for a client injured at an Idaho RV park, and why the work didn’t stop once the settlement check arrived.

The Fall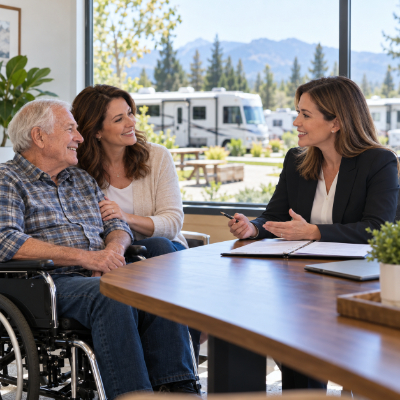
“Robert” (name changed to protect my client’s privacy) was in his mid-70s, widowed, and had sold his home. He’d bought an RV and planned to live out his retirement at a rural Idaho RV park, fishing and enjoying the outdoors near his children and grandchildren.
He had been at the park only a few days. On a cool November morning, he walked up a ramp to the raised platform at his RV site. He was preparing to meet the crew coming to hook up his propane. On his way back down the ramp, he took one step and slipped. There was no handrail.
He lay prone on the ramp for approximately 45 minutes before RV neighbors and the propane crew found him. Hypothermia was setting in. Air ambulance flew him to Boise.
The fall caused central cord syndrome, an injury to the spinal cord that left him with partial paralysis. He underwent neck surgery and extensive physical therapy. He regained some movement in his arms and legs, but not full control. He now uses a wheelchair and lives in assisted living.
Building the Case Before Filing Suit
I didn’t wait for a lawsuit to build my proof. I retained a human factors engineer who traveled to Idaho to inspect the ramp in person with me.
The conditions weren’t easy. Testing had to stop every time it started snowing and resume once it passed. The expert measured the ramp’s slope and surface friction. He found that the slope, the surface friction, and the missing handrail did not meet code or basic industry safety standards.
Before filing a lawsuit, I wrote up the expert’s findings and sent them directly to the insurance carrier’s defense attorney. The evidence was direct enough that formal litigation wasn’t necessary to resolve the claim.
The carrier tendered the full policy limits of $1,000,000.


Why I Didn’t Stop at the Settlement
A settlement check solves one problem. It can create another.
My client’s daughter had spent months working to qualify him for Medicaid, which was covering the cost of his long-term assisted living care. A lump-sum settlement would have made him ineligible for that coverage overnight, and the settlement alone wasn’t enough to privately fund a lifetime of care.
I brought in Sean Beck of Advanced Legal Planning, LLC, an attorney who specializes in Medicaid and public benefits planning. He structured the settlement in two parts. One portion went to my client’s children. Medicaid treats that transfer as a gift and imposes a period of ineligibility. The other portion went into an annuity timed to privately cover his care costs during that period.
Our firm covered the cost of this planning work ourselves, out of our fee and not out of our client’s settlement. I didn’t think it was right to hand a client a settlement and leave him to untangle a new financial problem on his own.
The Result
Full policy limits recovered, pre-lawsuit. A care plan designed to cover his care costs, and a share for his children, just as he wanted.
That’s the standard I hold every case to: know when to bring in the right expert, know the law well enough to make the other side’s decision easy, and don’t consider a case finished until my client’s life is actually taken care of, not just the claim.
If you or a family member has been injured on someone else’s property in Idaho, I’m happy to talk with you about your situation. Contact Hepworth Holzer, LLP today.
Verdicts & Settlements